Why a Share Secured Loan Might Be Your Best Option in Today’s Economy
I started researching share secured loans because two pieces of financial advice kept conflicting.
The first was to keep emergency savings intact. The second was to build a stronger credit history by responsibly using credit.
Following both recommendations at the same time was less straightforward than it sounded.
Using savings for an unexpected expense would prevent me from taking on debt, but it would also reduce my financial buffer. Taking an unsecured personal loan could leave the savings untouched, but the interest rate might make the decision unnecessarily expensive.
A share secured loan appeared to solve both problems. The borrower keeps money in a credit union savings account and uses that balance as collateral for a loan. The savings remain in the account, while the loan creates an opportunity to establish a record of monthly payments.
That sounded efficient. It also sounded slightly too convenient.
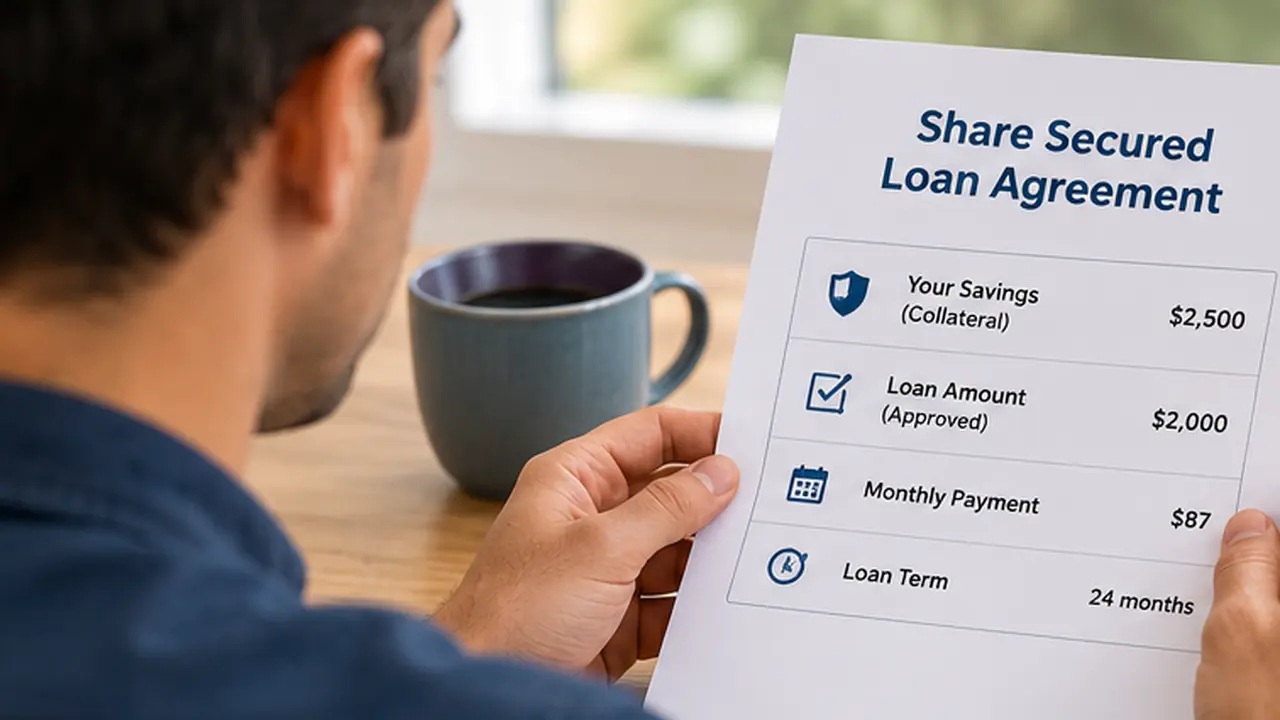
I therefore compared six share secured loan options from United States credit unions. I examined their publicly disclosed rates, collateral rules, repayment terms, fees, membership requirements, and credit-building claims. I also modeled a $2,000 borrowing scenario to see whether the structure made sense beyond the marketing language.
The conclusion was more nuanced than saying share secured loans are always good or that debt is always bad.
A carefully selected share secured loan can be useful in today’s economy. However, it is not free money. It does not guarantee a higher credit score, and it may temporarily restrict access to savings that a borrower considers available.
Table of Contents
A Note About This Comparison
This was a desk-based financial product comparison conducted using publicly available lender disclosures.
I did not open six loan accounts or claim to have personally borrowed from each institution. Instead, I evaluated the products using the same decision criteria and modeled how the costs would work in a realistic borrowing scenario.
Rates and eligibility requirements can change. An applicant’s final terms may differ from the rates advertised publicly. Readers should confirm the current annual percentage rate, fees, credit reporting policy, and collateral agreement directly with the credit union before applying.
Why I Decided to Test Share Secured Loans
My initial question was not simply, “What is a share secured loan?”
The more useful question was this:
Can someone use a share secured loan to build credit without creating more financial risk than the potential credit improvement is worth?
That distinction matters.
Many lender pages emphasize that a share secured loan can help establish or rebuild credit. That statement can be accurate when the lender reports payments to the credit bureaus and the borrower pays on time.
However, a new installment account can also create a hard inquiry, an additional monthly obligation, interest expense, and a temporary reduction in the average age of a borrower’s credit accounts.
A borrower could also miss a payment. That would undermine the original reason for opening the loan.
The Consumer Financial Protection Bureau explains that positive payment history can help build and maintain a strong credit profile. It also emphasizes that credit improvement takes time and consistent on-time payments. 1
FICO identifies payment history as the largest general category used in calculating a FICO Score. However, FICO also considers amounts owed, length of credit history, new credit, and credit mix. 2
This means a share secured loan build credit strategy cannot be judged by one factor alone.
I needed to test the entire structure.
What Is a Share Secured Loan in Practical Terms?
A share secured loan is an installment loan backed by money held in a credit union share savings account.
The word “share” refers to the member’s ownership share in the credit union. It does not mean that several people share the same loan.
When a credit union approves the loan, it places a hold on some or all of the pledged savings. The borrower receives the loan proceeds and repays the balance through scheduled monthly payments.
Depending on the credit union’s policy, portions of the savings may become available as the principal balance decreases. Other institutions may keep the full pledged amount restricted until the loan has been repaid.
The savings can usually continue earning dividends while pledged as collateral. However, the borrower may not be able to withdraw the restricted amount.
This structure reduces the credit union’s risk. If the borrower defaults, the institution may apply the pledged funds to the unpaid loan balance, subject to the loan agreement and applicable law.
Is a Shared Secured Loan the Same Product?
People frequently search for “shared secured loan” or ask, “What is a shared secured loan?”
In most cases, they mean a share secured loan.
“Shared secured loan” is a common wording variation, but “share secured loan” is the standard term used by credit unions. The loan is secured by funds in a member’s share account.
How I Evaluated the Six Loan Options
I did not want to rank lenders based only on the lowest advertised APR. A low headline rate can hide an inconvenient term, restricted membership, slow collateral release, or unclear credit reporting.
I used six evaluation criteria.
1. Total Borrowing Cost
I looked at the advertised APR or rate formula, not just whether the lender described its rates as competitive.
I also checked for application and origination fees when disclosed.
2. Credit Bureau Reporting
A share secured loan cannot serve its intended credit-building purpose unless the payment history appears on the borrower’s credit reports.
I gave more weight to lenders that explicitly stated that they report repayment activity.
3. Collateral Release Policy
I checked whether pledged savings become available as the borrower pays down the principal.
Gradual release improves liquidity. A full hold until final repayment can make the loan more restrictive.
4. Loan Amount and Term
A large maximum loan is not automatically an advantage.
For credit building, a smaller loan with an affordable payment may be more appropriate. Long terms reduce the monthly payment but increase total interest and keep the collateral restricted longer.
5. Fees and Transparency
I looked for clearly displayed APRs, minimum amounts, maximum amounts, terms, and fee information.
When details were unavailable, I treated that as information the applicant would need to confirm directly.
6. Membership Eligibility
A secured loan credit union product is usually available only to members.
Credit union membership may depend on geographic location, employment, military connection, family relationship, association membership, or another field-of-membership condition.
The best-looking product has little practical value when the applicant cannot join the institution.
The Six Share Secured Loan Options I Compared
The following information reflects the public terms displayed when I conducted the comparison. Advertised rates do not guarantee approval or a particular final APR.
| Credit union | Publicly disclosed pricing | Amount and term information | Notable feature |
|---|---|---|---|
| Global Credit Union | APR as low as 2.10% | Based on qualifying savings or certificate funds | No application or origination fee disclosed |
| Navy Federal Credit Union | Share account rate plus 2.00% | Amount tied to the pledged savings balance | Fewer shares remain restricted as the balance declines |
| 1st United Credit Union | 3.03% APR | $500 to $80,000, with terms from 6 to 96 months | Principal payments gradually release pledged savings |
| First Tech Federal Credit Union | Savings account rate plus 3.00% | $500 to $500,000 | Fixed payments and a published representative example |
| Space Coast Credit Union | Savings dividend rate plus 3.00% | Up to 100% of eligible savings, with terms up to 120 months | No application fee and access to a FICO Score |
| Credit Union West | Dividend rate plus 3.00% | Amount based on share balance, with terms up to 120 months | Savings continue earning dividends while pledged |
Global Credit Union
Global Credit Union displayed one of the lowest headline rates in the group, with a secured loan APR as low as 2.10% when checked.
It also stated that secured personal loans do not carry application or origination fees. Borrowers can secure the loan with a Global savings account or certificate account and continue earning dividends on the collateral. 3
The headline APR was attractive, but “as low as” still matters. Applicants should confirm the actual rate, loan term, collateral release schedule, and credit reporting practices before accepting the offer.
Membership eligibility may also depend on location, employment, organizational affiliation, Department of Defense employment, or family relationships. 4
Navy Federal Credit Union
Navy Federal disclosed a savings secured loan rate based on the applicable share rate plus 2.00%. 5
Its collateral structure stood out. The required secured share balance decreases as the outstanding loan balance declines. This can return access to portions of the savings during repayment rather than waiting until the final payment. 6
The main limitation is membership.
Navy Federal primarily serves active-duty servicemembers, veterans, Department of Defense personnel, and qualifying family or household members. 7
For an eligible borrower, its rate formula and declining collateral requirement make it worth examining.
1st United Credit Union
1st United provided some of the clearest public information in the comparison.
Its share secured loan page displayed a 3.03% APR, a $500 minimum, an $80,000 maximum, and terms from 6 to 96 months. It also stated that the hold on the savings balance decreases as principal payments are made. 8
More importantly for a borrower focused on credit, the lender explicitly stated that repayment behavior is reported to the credit bureaus.
This combination of a clear APR, gradual collateral release, and explicit reporting made the product easy to evaluate.
The limitation is that published rates can change. Applicants also need to confirm whether reporting goes to one, two, or all three major nationwide credit reporting companies.
First Tech Federal Credit Union
First Tech advertised a savings secured loan rate based on the savings account rate plus 3.00%. Its published loan range was unusually broad, from $500 to $500,000.
The credit union also provided a representative example showing a 3.88% APR for a 60-month savings secured loan. 9
The broad maximum may be useful for borrowers with substantial savings, but it is not necessarily relevant to someone who only wants to establish payment history.
Using $20,000 or $50,000 of savings as collateral merely to improve credit would create unnecessary exposure. Credit-building borrowers should usually focus on the smallest amount that achieves the intended purpose while keeping the monthly payment manageable.
Space Coast Credit Union
Space Coast Credit Union allowed borrowers to request up to 100% of the qualifying balance in a regular savings account or certificate.
Its public disclosures stated that a share secured loan could run for up to 120 months. The rate was described as 3.00 percentage points above the variable dividend rate on the savings account. The credit union also disclosed no application fee. 10
The long maximum term creates flexibility, but it also creates a temptation.
A 120-month term may produce a small monthly payment. It can also keep savings restricted for years and increase total interest expense. For a small credit-building loan, such a long term would rarely be my first choice.
Membership is primarily available to people who live or work in eligible Florida counties and relatives of existing members. 11
Credit Union West
Credit Union West disclosed a share secured loan rate equal to the applicable dividend rate plus 3.00%. Terms could extend up to 120 months, with the available loan amount based on the member’s share account balance. 12
The pledged savings continue earning dividends during repayment.
Again, the long term is better viewed as flexibility than as a recommendation. The appropriate term depends on the borrower’s cash flow, purpose, and willingness to keep savings restricted.
The $2,000 Test That Changed My View
Comparing lender pages was useful, but it did not answer the main question.
I needed to compare the actual tradeoffs.
I modeled a borrower with:
- $3,500 in savings
- A thin or damaged credit history
- A $2,000 expense
- Stable income
- No recent late payments
- A goal of preserving part of the emergency fund
I compared four approaches.
Approach 1: Withdraw $2,000 From Savings
This is the simplest option.
There is no loan application, no interest, no monthly payment, and no risk of a missed loan payment.
However, the savings balance falls from $3,500 to $1,500. The transaction also creates no new installment payment history because spending savings is not borrowing.
This approach worked best when the expense was urgent and the remaining $1,500 was still enough to cover foreseeable emergencies.
It worked poorly when using the savings would leave the borrower unable to handle rent, medical costs, transportation repairs, or another immediate expense.
Approach 2: Take a $2,000 Share Secured Loan
For illustration, I modeled a $2,000 loan at a fixed 3.50% APR.
These figures are examples, not quoted terms from a specific lender.
Twelve-Month Term
- Estimated monthly payment: $169.84
- Estimated total interest: $38.12
- Collateral initially restricted: approximately $2,000
Twenty-Four-Month Term
- Estimated monthly payment: $86.41
- Estimated total interest: $73.73
- Collateral initially restricted: approximately $2,000
The 24-month term reduced the payment by about half, but it nearly doubled the interest expense. It could also keep part of the savings restricted for twice as long.
The 12-month loan was financially cheaper, but only when the borrower could comfortably handle the higher payment.
This was the first major lesson from the experiment.
The shortest term is not always the safest choice. A lower total cost is irrelevant if the payment is so high that the borrower risks being late.
Approach 3: Use a Secured Credit Card
A secured credit card can also help establish credit. The borrower provides a refundable deposit that usually determines the credit limit.
This approach may be better when the primary goal is building a revolving credit history through small, regular purchases.
A secured card can potentially cost little or no interest when the borrower pays the statement balance in full every month. However, it introduces credit utilization, variable spending, and the risk of carrying a high-interest balance.
A share secured loan is more predictable. It provides one fixed amount, one repayment schedule, and a defined payoff date.
A secured card offers more flexibility, but it requires stronger day-to-day spending discipline.
Approach 4: Use a Credit-Builder Loan
A credit-builder loan works differently.
Instead of giving the borrower immediate access to the proceeds, the lender generally holds the money in an account while the borrower makes monthly payments. The borrower receives the accumulated funds after completing the loan.
The CFPB identifies credit-builder loans as one way to build credit and savings simultaneously. 13
A CFPB evaluation found that credit-builder loans appeared more effective for participants who entered the study without existing debt. The study also found that an additional required payment could make it harder for some participants to keep up with other obligations. 14
This option worked best when the borrower did not need immediate access to the loan proceeds.
It did not solve the original $2,000 expense because the money remained restricted.
What Surprised Me During the Comparison
Several initial assumptions did not survive the test.
The Lowest APR Was Not Automatically the Best Offer
I expected the lender with the lowest advertised secured loan rates to be the obvious winner.
It was not.
A difference of one percentage point on a small, short-term loan may change the total interest by only a modest amount. By contrast, an origination fee, unclear reporting policy, or restrictive collateral release rule could have a larger practical effect.
For a credit-building borrower, I would prioritize the following:
- Confirmed reporting to major credit bureaus
- No application or origination fee
- Affordable monthly payment
- Gradual collateral release
- Transparent fixed APR
- A short but manageable term
The headline APR still matters, but it belongs inside a larger decision.
Collateral Release Mattered More Than I Expected
Initially, I treated every savings-backed loan as essentially the same.
That was a mistake.
Consider two $2,000 loans.
With the first lender, $2,000 remains frozen until the final payment. With the second lender, part of the savings becomes available each month as the principal declines.
Both loans may have the same APR. Their effect on the borrower’s liquidity is very different.
For someone using emergency savings as collateral, gradual release is a meaningful protection.
Before applying, I would ask:
- Does the credit union release funds as principal is repaid?
- How frequently does the release occur?
- Does the entire original deposit remain restricted?
- Can additional savings be deposited and withdrawn normally?
- Does the collateral secure only this loan?
The last question deserves particular attention. Federal lending disclosures may state that collateral securing one obligation can also secure other loans with the same institution. Borrowers should read the security agreement rather than assuming that the pledged account applies only to one product. 15
A Share Secured Loan Does Not Guarantee a Credit Score Increase
The phrase “share secured loan build credit” can create an unrealistic expectation.
A lender can report the account. It cannot guarantee a specific score increase.
The effect depends on the borrower’s entire credit file, including existing debts, missed payments, account age, utilization, recent applications, and the scoring model being used.
Opening a new loan can also create a hard inquiry and reduce the average age of accounts. These effects may temporarily offset part of the benefit from adding an installment account.
The reliable benefit is narrower.
An accurately reported share secured loan gives the borrower an opportunity to create positive installment payment history. Whether that produces a 5-point, 20-point, or larger score change cannot be predicted responsibly without analyzing the complete credit file.
Borrowing Against Savings Still Reduces Liquidity
Lender marketing often says that borrowers can keep their savings.
Technically, the savings remain in the account.
Practically, pledged funds may not be available for withdrawal.
That distinction is important.
A person with $3,500 in savings and a $2,000 hold does not have the same immediate liquidity as someone with an unrestricted $3,500 balance.
I would not pledge an entire emergency fund. I would keep enough unencumbered cash to cover essential expenses and at least one unexpected disruption.
Long Terms Can Turn a Cheap Loan Into an Inefficient One
Share secured loan rates are often lower than unsecured personal loan rates because the institution holds cash collateral.
That does not make the repayment term irrelevant.
A long term can:
- Increase total interest
- Delay full access to the pledged savings
- Keep an unnecessary monthly obligation open
- Make a small purchase feel cheaper than it is
- Encourage a borrower to take a larger loan
The better term is not necessarily the shortest available. It is the shortest term with a payment that remains comfortable after rent, utilities, food, transportation, insurance, and existing debt payments.
Credit Union Eligibility Can Be the Real Bottleneck
Several attractive products were unavailable to a large portion of the general public.
Navy Federal has military and Department of Defense-related eligibility rules. Space Coast Credit Union primarily serves qualifying Florida communities. Other institutions use employer, association, family, or regional requirements.
This means a national “best share secured loan” ranking can be misleading.
The best starting point is often the credit union the borrower can already join, especially when it offers transparent pricing and reports payments to the major credit bureaus.
What Actually Worked Best
The best result was not one particular lender.
It was a specific loan structure.
For someone who already has savings and wants to establish installment credit, I would look for a share secured loan with:
- A loan amount between $500 and $2,000
- No application or origination fee
- A fixed APR close to the savings dividend rate plus 2 to 3 percentage points
- Reporting to all three major credit bureaus
- A term between 6 and 24 months
- An affordable payment
- Automatic payment capability
- Gradual release of pledged funds
- No prepayment penalty
- Clear collateral and default terms
A small loan is usually sufficient for credit-building purposes. Borrowing more does not automatically produce a larger credit score benefit.
The payment history matters more than the size of the balance.
When a Share Secured Loan Might Be Your Best Option
A share secured loan may be a strong option when:
- You already have sufficient savings at an eligible credit union.
- Using the savings directly would leave your emergency fund too low.
- You need access to the loan proceeds immediately.
- The lender confirms positive payment reporting.
- The APR and fees are modest.
- The monthly payment fits comfortably within your budget.
- You want a fixed installment account rather than a revolving credit card.
- You can keep additional emergency cash outside the pledged balance.
When I Would Not Choose One
I would avoid a share secured loan when:
- The pledged money represented my entire emergency fund.
- I could not reliably make the monthly payment.
- The lender did not report positive payments.
- The loan carried substantial fees.
- The term was unnecessarily long.
- I was taking the loan only to chase a specific credit score.
- I already had several open installment loans.
- I needed unrestricted access to the savings.
- I could pay the expense from savings without weakening my financial safety.
- A no-fee secured credit card better matched my credit-building goal.
My Pre-Application Checklist
Before applying for a share secured loan, I would ask the credit union these questions in writing.
Credit Reporting
- Do you report the loan to Equifax, Experian, and TransUnion?
- When does reporting begin?
- How is the account classified on the credit report?
- Do you report both positive and negative payment history?
Rate and Cost
- What is my exact APR?
- Is the rate fixed?
- Is the APR calculated as the share dividend rate plus a margin?
- Are there application, origination, administrative, or early payoff fees?
- What is the total finance charge over the proposed term?
The CFPB notes that personal installment loans may include fees in addition to interest, so borrowers should review the full cost rather than focusing exclusively on the stated rate. 16
Collateral
- How much of my savings will be restricted?
- Does the restricted amount decline as I repay principal?
- When are released funds available for withdrawal?
- Will the savings continue earning dividends?
- Can the credit union use this collateral for another debt?
- What happens to the pledged funds if I miss a payment?
Repayment
- Can I set up automatic payments?
- Is there a grace period?
- Is there a late fee?
- Can I pay the loan off early without a penalty?
- Will early payoff affect how the loan is reported?
Membership
- Am I eligible to join?
- Is a minimum savings deposit required?
- Are there membership or account maintenance fees?
- Must I maintain membership after the loan is paid?
How I Would Use the Loan to Build Credit
The loan itself is only the vehicle. The repayment system determines whether it helps.
My process would be:
- Check all three credit reports before applying.
- Correct any material errors.
- Borrow only the amount needed.
- Choose a payment comfortably below the maximum I could afford.
- Set up automatic payment for at least the minimum due.
- Keep one monthly payment in reserve.
- Confirm that the first payment appears on my credit reports.
- Continue paying all other accounts on time.
- Avoid opening several new accounts simultaneously.
- Review the reports again after three to six months.
Consumers can obtain their official free credit reports through AnnualCreditReport.com. 17
The National Credit Union Administration also insures qualifying deposits at federally insured credit unions, generally up to the applicable federal limits. Insurance protects eligible deposits if the institution fails. It does not protect a borrower from the consequences of defaulting on a loan secured by those deposits. 18
Frequently Asked Questions
What Is a Share Secured Loan?
A share secured loan is an installment loan backed by money in a credit union share savings account. The credit union places a hold on the pledged funds and provides the borrower with loan proceeds. The borrower then repays the loan through scheduled payments.
What Is a Shared Secured Loan?
“Shared secured loan” usually refers to the same product, but the standard term is “share secured loan.” The word “share” refers to a member’s ownership share and savings account at a credit union.
Can a Share Secured Loan Build Credit?
It can help establish positive installment payment history when the lender reports the account and the borrower makes every payment on time.
It does not guarantee a particular credit score increase. The result depends on the borrower’s broader credit profile and the scoring model.
Are Secured Loan Rates Always Lower?
They are often lower than comparable unsecured loan rates because the lender holds collateral. However, applicants should compare the APR, fees, repayment term, and savings dividend rate.
A lower APR does not automatically produce the lowest overall cost.
Can I Withdraw My Savings During the Loan?
Usually, the pledged portion is restricted.
Some credit unions release portions as the principal decreases. Others may keep the entire pledged amount restricted until repayment is complete. Confirm the release policy before signing.
Will the Savings Still Earn Dividends?
Many share secured loan programs allow the pledged savings to continue earning dividends. The actual rate and account rules depend on the institution.
Does Applying Require a Credit Check?
Policies vary.
Some credit unions conduct a hard credit inquiry even when the loan is fully secured. Others may use a different underwriting process. Ask whether the application will create a hard or soft inquiry before authorizing the credit check.
Can I Use a Share Secured Loan to Consolidate Debt?
Some lenders allow the proceeds to be used for debt consolidation.
However, using savings as collateral to pay unsecured debt changes the risk. The borrower converts debt that was not backed by savings into an obligation tied to a deposit account.
The decision should be based on the total interest savings, fees, repayment discipline, and the amount of emergency liquidity that remains available.
Final Takeaways
I began this comparison expecting to find one share secured loan that was clearly better than the others.
Instead, I found that the product’s design matters more than its brand.
The most useful share secured loan is usually small, transparent, inexpensive, and easy to repay. It reports to the major credit bureaus, releases collateral as principal declines, and does not consume the borrower’s entire emergency fund.
My main mistake at the beginning was treating the savings balance as fully preserved.
The money remains in the account, but it may not remain available. That liquidity cost should be evaluated as seriously as the APR.
I also underestimated the importance of credit reporting. A low-rate loan that does not report positive payments would fail the central goal of a credit-building strategy.
For borrowers with existing savings, stable income, and a thin credit file, a carefully selected share secured loan can be a practical option in today’s economy. It allows them to access funds, preserve ownership of their savings, and establish installment payment history.
For borrowers with unstable cash flow or very limited emergency savings, the same product can create a monthly obligation and restrict the cash they may need most.
The best decision is therefore not to borrow the largest amount available or choose the longest term.
It is to borrow the smallest useful amount, maintain enough unrestricted savings, and create a repayment plan that leaves little room for a missed payment.