I Tried to Refinance My Car Loan: Here’s What Actually Worked
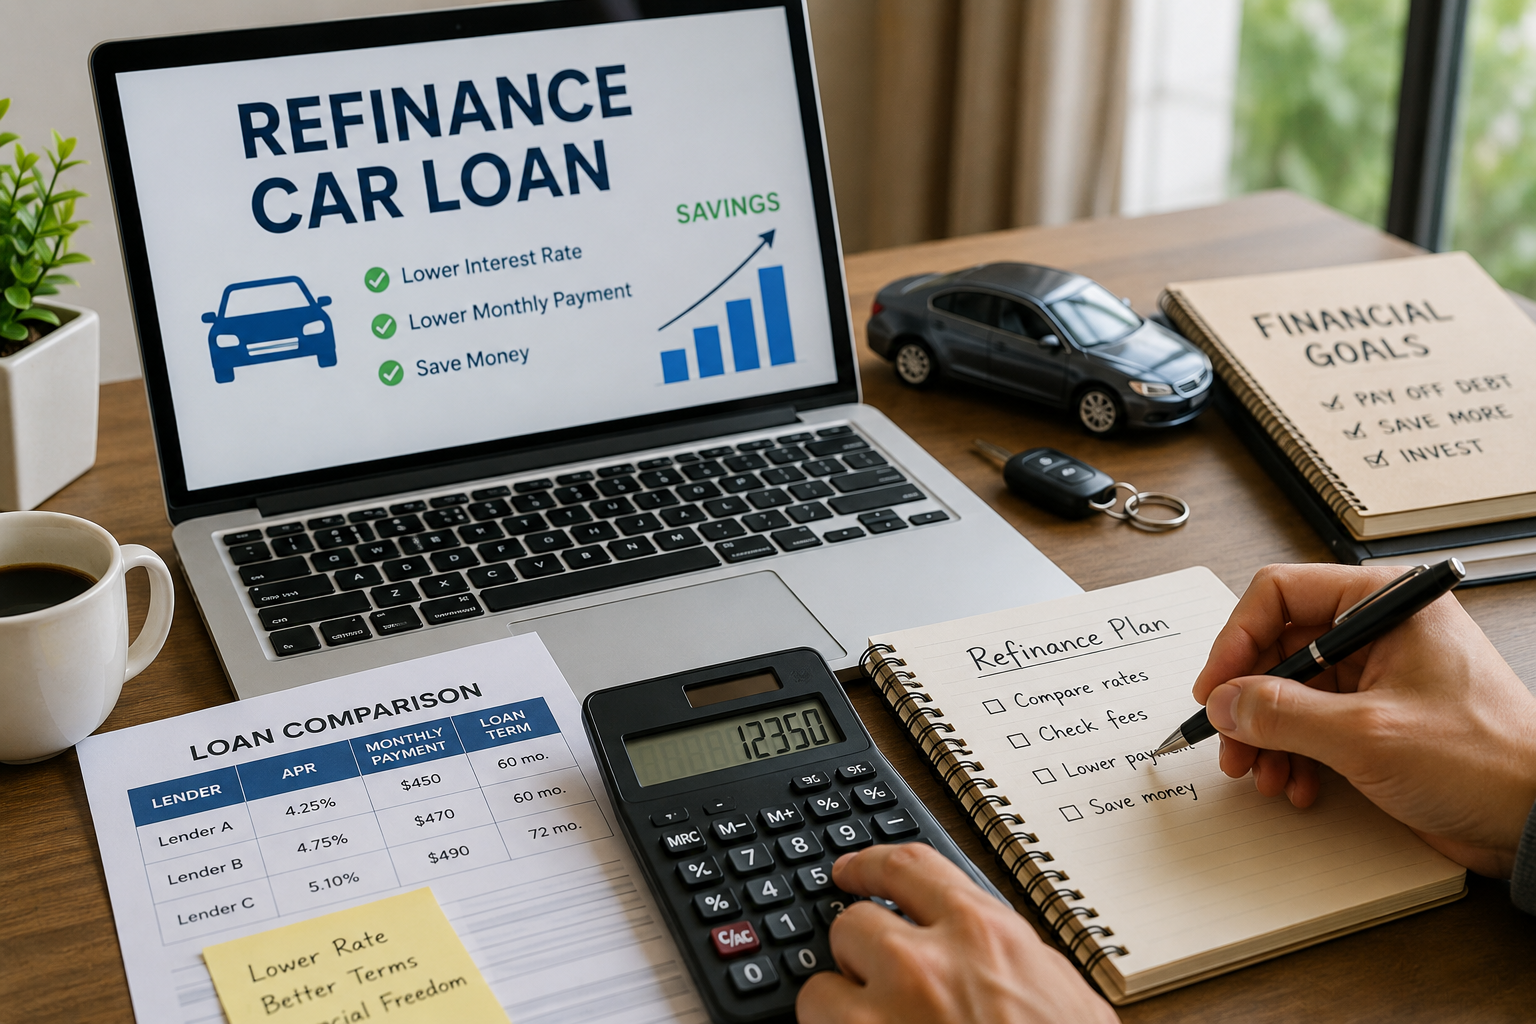
I started looking into a refinance car loan after one uncomfortable moment: I looked at my monthly payment and realized I had no idea whether it was still a good deal.
The payment had become normal. It came out every month, I accepted it, and I moved on. But when I looked more closely, I noticed something I had ignored for too long. I knew my monthly payment, but I did not really understand my APR, remaining loan term, total interest cost, or whether another lender could offer better terms.
That bothered me.
At first, I assumed getting a refinance car loan would be simple. If another lender offered a lower rate, I would take it. If not, I would keep my current loan. But the more I researched auto loan refinancing, the more complicated the decision became.
A lower monthly payment did not always mean a better deal.
A lower APR did not always guarantee meaningful savings.
A longer loan term could make the payment feel easier but increase the total cost.
Some lenders looked attractive at first, but the details were less clear once fees, eligibility rules, and vehicle requirements entered the picture.
So I decided to treat the process like a small finance experiment. I reviewed my current loan, checked my car’s value, compared refinance offers, looked at possible fees, and tested different scenarios before deciding what actually made sense.
This is what I learned.
Table of Contents
Why I Decided to Get a Refinance Car Loan
The main reason was simple: I wanted to know whether I was overpaying on my auto debt.
When I first financed the car, I was focused on getting approved and keeping the monthly payment manageable. I looked at the payment more than the total cost of the loan. At the time, that felt practical.
Later, I realized that was not enough.
A car loan is not just one number. It has several moving parts:
-
Monthly payment
-
APR
-
Remaining balance
-
Remaining term
-
Fees
-
Vehicle value
-
Credit score
-
Total interest cost
Once I saw all of those pieces together, I understood why a refinance car loan needed more than a quick yes-or-no answer. My goal was not just to lower the payment. My real goal was to reduce unnecessary cost without creating a worse long-term situation.
What I Expected Before Testing a Refinance Car Loan
Before comparing lenders, I expected three things.
First, I expected that the lender with the lowest monthly payment would be the best option. Second, I expected that refinancing would automatically save money if the APR was lower. Third, I expected that the process would be mostly the same across lenders.
All three assumptions turned out to be incomplete.
The lowest monthly payment was not always the smartest choice. A lower APR helped, but only if the loan term and fees also made sense. And different lenders had different requirements for vehicle age, mileage, loan balance, title status, and credit profile.
That was the first big lesson. Finding a smart refinance car loan is not just about finding a lower payment. It is about comparing the full loan.
What I Tested for a Refinance Car Loan
I compared several refinancing approaches rather than jumping straight into one application.
My Current Lender Offer for a Refinance Car Loan
I started with my existing lender because it seemed convenient. They already had my loan details, payment history, and account information. The advantage was simplicity. The downside was that convenience did not guarantee the best rate.
Checking Credit Union Refinance Car Loan Rates
Next, I checked a credit union because credit unions often compete on rates and member service. I wanted to see whether a more traditional financial institution could offer a better overall deal.
An Online Auto Refinance Marketplace Experience
I also reviewed online refinance marketplaces that allow borrowers to compare multiple offers. The benefit was speed. The downside was that some details were harder to understand upfront, especially fees and final approval conditions.
Looking at a Traditional Bank Deal
Finally, I checked a traditional bank to compare how its offer looked against the other options. I wanted to understand whether a well-known institution would provide more clarity, better rates, or fewer surprises.
My Evaluation Criteria for a Refinance Car Loan
To avoid choosing based only on monthly payment, I used a simple checklist. I compared each option based on:
-
APR
-
Monthly payment
-
Remaining loan term
-
Total interest cost
-
Fees
-
Credit check impact
-
Vehicle eligibility
-
Application process
-
Customer support
-
Flexibility if I wanted to pay off the loan early
This helped me avoid one of the biggest mistakes in auto loan refinancing: focusing only on the payment.
A lower payment can help your budget, but it may come from extending the loan. If the new term is much longer, you may pay more over time even though the monthly bill looks better.
First Thing I Checked: My Current Refinance Car Loan Status
Before looking at new offers, I reviewed my existing loan. I looked at the current balance, current APR, monthly payment, remaining months, payoff amount, any prepayment penalty, and whether the loan was close to being paid off.
This step mattered more than I expected.
If a car loan is almost paid off, a refinance car loan may not save much because much of the interest may already have been paid earlier in the loan. On the other hand, if there is still a meaningful balance and several years left, refinancing may create more room for savings. In my case, the loan still had enough time left to make comparison worthwhile.
The Second Thing I Checked: My Car’s Value
After reviewing the loan, I checked the car’s estimated value. This was important because lenders often look at the relationship between the loan balance and the car’s value.
If you owe more than the car is worth, applying for a refinance car loan can become harder or less attractive. This is often called being upside down or underwater on the loan. That situation does not automatically make refinancing impossible, but it can reduce options.
Fortunately, I checked my vehicle value online via Kelley Blue Book and found my loan balance was not far above the estimated value. That gave me enough room to continue comparing offers.
The Third Thing I Checked: My Credit Profile
I also reviewed my credit situation before applying. This mattered because credit can affect the APR offered by lenders. If your credit score has improved since you first took out the loan, refinancing may help you qualify for a better rate.
However, I also wanted to avoid unnecessary hard credit checks. So I looked for prequalification tools where possible. Prequalification does not always guarantee final approval, but it can help you understand potential rates before submitting a full application.
This step helped me avoid rushing into a formal application before knowing whether a refinance car loan was likely to help my budget.
What Happened When I Compared Offers
Once I started comparing offers, I noticed something interesting. The offers looked similar at first, but the details were different.
-
One lender offered a lower monthly payment, but the term was longer than I wanted.
-
Another lender offered a lower APR, but the monthly payment did not drop much because the term was shorter.
-
A third option looked easy, but the fee details were less clear.
-
The credit union was not the fastest option, but it gave me one of the clearest breakdowns.
-
The online marketplace was convenient, but I had to pay closer attention to the final terms from each partner lender.
-
My current lender was easy to deal with, but the offer was not the most competitive.
That surprised me. I expected convenience to be the winning factor. Instead, clarity and total cost mattered more.
What Surprised Me Most About a Refinance Car Loan
The biggest surprise was that a refinance car loan can solve one problem while creating another.
For example, lowering the monthly payment can help your short-term budget. That matters if your current payment is causing stress. However, if the lower payment comes from stretching the loan over a longer period, you may pay more interest overall.
That does not mean a longer term is always bad. Sometimes cash flow matters more than total cost, especially if someone needs immediate budget relief. But it does mean you should understand the tradeoff.
The second surprise was how much the remaining term mattered. If you are near the end of your loan, refinancing may not be worth the effort. The third surprise was that lender requirements vary more than I expected. Vehicle mileage, age, title status, loan balance, and loan-to-value ratio can all affect eligibility.
Mistakes I Almost Made
I nearly made three mistakes during the process.
Mistake 1: Looking Only at the Monthly Payment
The first offer I liked had the lowest monthly payment. At first, it looked like the obvious winner. Then I noticed the loan term was longer. Once I calculated the total cost, the offer looked less attractive.
Mistake 2: Ignoring Fees
Some refinancing offers may include title fees, processing fees, administrative fees, or other costs. Even small fees can reduce the benefit of refinancing. Before accepting any offer, I compared the estimated savings against the cost of switching loans.
Mistake 3: Assuming a Lower APR Always Wins
A lower APR is important, but it should not be viewed alone. The loan term, fees, and remaining balance all matter. A lower APR with a longer term may not save as much as expected.
What Actually Worked Best
The best option was not the one with the lowest monthly payment. The best option was the one that lowered the APR while keeping the remaining term close to my current loan.
That mattered because it reduced interest cost without stretching the debt too far into the future. In simple terms, the winning refinance car loan offer did three things:
-
Reduced the APR
-
Kept the term reasonable
-
Avoided unnecessary fees
That combination created real savings without making the loan feel artificially cheaper.
Signs That a Refinance Car Loan Makes Sense for You
Based on my experience, looking for a refinance car loan may make sense when:
-
Your credit has improved since you first bought the vehicle
-
Market rates are better than when you first borrowed
-
Your current APR is high
-
You still have enough loan balance left
-
You are not near the end of the loan
-
Your car meets lender age and mileage requirements
-
The savings are larger than any fees
-
You can avoid extending the loan too much
The strongest case is usually when you can lower the APR and keep the term similar. That gives you a better chance of reducing total interest instead of only reducing the monthly payment.
When I Would Avoid Refinancing
I would be more cautious about car refinancing if:
-
The loan is almost paid off
-
The new term is much longer
-
Fees cancel out the savings
-
The APR is not meaningfully better
-
The car is worth less than the loan balance
-
A major mortgage or credit application is coming soon
-
The offer is not clear about total cost
Refinancing can be useful, but it is not automatically smart. The math has to work, and safety rules always apply.
My Simple Refinance Checklist
If I were doing this again, I would use this checklist before choosing a refinance car loan.
-
Step 1: Review the current loan – Check the balance, APR, payment, remaining term, payoff amount, and fees.
-
Step 2: Estimate the car’s value – Compare the loan balance with the vehicle value.
-
Step 3: Check credit health – Look for signs that your credit profile has improved since the original loan.
-
Step 4: Compare several lenders – Check banks, credit unions, online lenders, and your current lender.
-
Step 5: Compare total cost – Do not choose based only on monthly payment.
-
Step 6: Watch the loan term – A longer term may lower the payment but increase total interest.
-
Step 7: Review fees – Include title, processing, documentation, and other costs.
-
Step 8: Decide based on your goal – Choose based on whether you want lower monthly payments, lower total cost, or faster payoff.
The Tradeoff Between Lower Payment and Lower Total Cost
This was the most important part of the experiment. There are two different goals when managing a refinance car loan.
One goal is payment relief. The other goal is total savings.
If your monthly car payment is causing financial pressure, lowering the payment may be the priority. In that case, a longer term may be acceptable as long as you understand the cost. If your goal is to save money overall, you should focus on reducing APR and avoiding a much longer term.
Both goals are valid. The mistake is confusing one for the other.
What I Would Do Differently Next Time
Next time, I would start with the math sooner. I spent too much time looking at lender names and not enough time comparing the full loan picture. I would also prepare documents earlier, including:
-
Current loan details
-
Payoff amount
-
Vehicle registration
-
Proof of insurance
-
Proof of income
-
Estimated vehicle value
Having those ready would make the process smoother. Finally, I would compare offers within a shorter window. That helps keep the process organized and may reduce the impact of multiple credit checks when formal applications are involved.
Frequently Asked Questions
What does it mean to refinance a car loan?
Refinancing a car loan means replacing your current auto loan with a new loan. The new loan pays off the old one and gives you new terms, such as a different APR, payment, or repayment period.
Is refinancing a car loan worth it?
It can be worth it if the new loan lowers your APR, reduces total interest, improves your monthly budget, or creates better loan terms. However, it depends on fees, loan term, credit profile, and vehicle eligibility.
Does refinancing a car loan hurt your credit?
It can cause a temporary credit score impact if the lender performs a hard inquiry. However, the long-term effect depends on your overall credit behavior and whether you continue making payments on time.
Can a refinance car loan lower my monthly car payment?
Yes, it can lower your monthly payment if you qualify for a lower APR or choose a longer repayment term. However, extending the term may increase total interest.
Should I refinance with my current lender?
Your current lender may be convenient, but it is still worth comparing offers from banks, credit unions, and online lenders. Convenience does not always mean the best deal.
What should I compare before refinancing?
Compare APR, monthly payment, loan term, fees, total interest, payoff amount, and lender requirements.
Final Takeaways
Refinancing my car loan taught me that the best offer is not always the one that looks cheapest at first. A lower monthly payment can be helpful, but it does not automatically mean the loan is better.
The real question is whether the new loan improves your financial situation without creating a bigger long-term cost. For me, the best option was a refinance car loan offer that lowered the APR, kept the term reasonable, and avoided unnecessary fees. That balance mattered more than chasing the lowest payment.
If I were giving advice to someone considering auto loan refinancing, I would say this: Run the numbers first, compare more than one lender, look beyond the monthly payment, and make sure the refinance matches your actual goal.
Sometimes the best financial decision is to refinance. Other times, the smarter move is to keep the loan you already have. The only way to know is to compare the full cost honestly. For more updates, feel free to visit our About Us page or check out the Privacy Policy on iskconofescondido.com.