Discover How You Can Use 401k to Buy a House Without Costly Mistakes
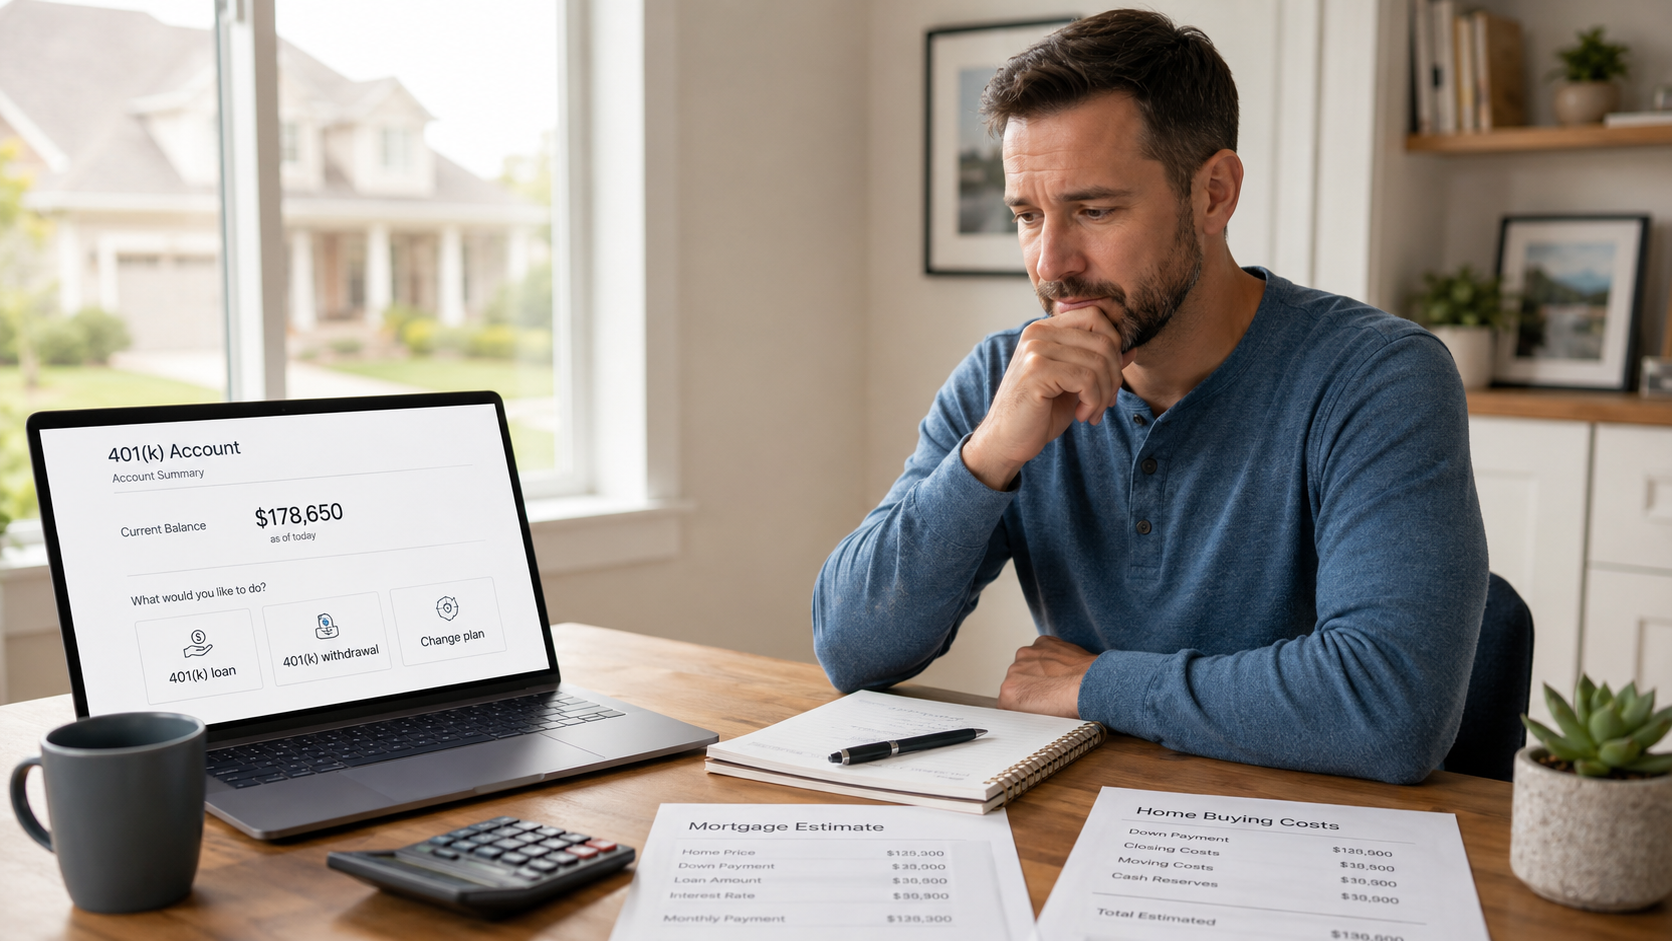
Table of Contents
The house was not the hard part. The cash gap was.
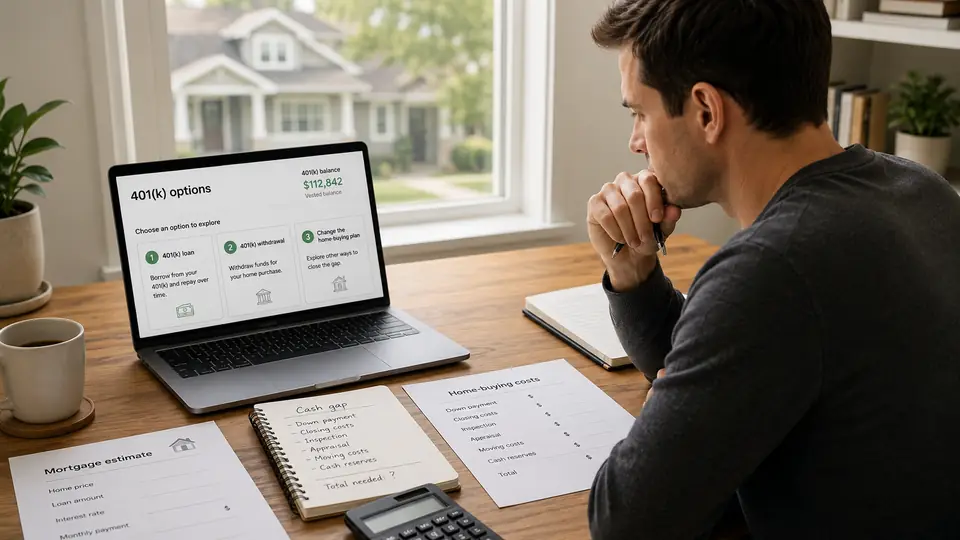
The first time I seriously asked, “can I use 401k to buy a house?”, it was not because I wanted to raid retirement money casually.
It was because the numbers were close, but not close enough.
The mortgage estimate looked possible. The monthly payment was uncomfortable, but not absurd. The real problem was the upfront cash. Down payment, closing costs, inspection, appraisal, moving costs, cash reserves, and the small expenses that do not feel small when they all land in the same month.
That was the moment the 401(k) started to look tempting.
It was sitting there on the dashboard.
Not exactly “available,” but visible.
And that visibility made the decision harder.
I found a lot of advice online. Some articles made using 401(k) money sound like a clever bridge to homeownership. Others made it sound like the kind of decision future-you would resent. Reddit threads were even messier: some people said they did it and had no regrets, while others said it delayed their retirement progress for years.
So I treated it like a financial stress test.
I compared three real options:
- Taking a 401(k) loan.
- Taking a 401(k) withdrawal for home purchase.
- Not touching the 401(k) and changing the home-buying plan.
I was not trying to find the most aggressive way to buy a house.
I was trying to find the least damaging way to make the decision.
This article is not personal financial, tax, or legal advice. A 401(k) plan is governed by plan rules and federal tax rules, so anyone considering this should review their plan documents and speak with a qualified financial or tax professional.
Why I decided to test the 401(k) idea
At first, the question sounded simple:
Can I use my 401(k) to buy a house?
The short answer is yes, in some cases.
But the better question is:
Should I use my 401(k) to buy a house, and if so, which method creates the least long-term damage?
That is where the decision gets complicated.
A 401(k) is not a normal savings account. It is a retirement account with tax rules, plan restrictions, possible penalties, repayment terms, and long-term opportunity costs.
The IRS explains that hardship distributions, early withdrawals, and loans have different rules. A hardship distribution is a withdrawal made because of an immediate and heavy financial need, and it is generally taxable and not repaid to the account [1]. The IRS also states that hardship distributions may be subject to income tax and a 10% additional tax on early distributions, and employees cannot repay hardship distributions back into the plan [2].
That one detail changed how I saw the decision.
A withdrawal felt simple because it did not create a monthly loan payment.
But it also permanently removed money from the retirement account.
A loan felt more controlled because the money could be paid back.
But it created repayment pressure and job-change risk.
Before testing the options, I expected the 401(k) loan to be the obvious winner.
By the end, I still thought it was usually better than a withdrawal, but only under strict conditions.
What I tested
I compared four approaches a U.S. homebuyer might consider.
1. Borrow from 401(k) to buy house
This means taking a loan from your 401(k), if your plan allows it.
The IRS says plan loans are not required, but if a plan allows loans, the maximum amount is generally the lesser of 50% of your vested account balance or $50,000. There is also a possible exception where a participant may borrow up to $10,000 if 50% of the vested account balance is less than $10,000, though plans are not required to include that exception [3].
This option was appealing because it looked like a way to access cash without triggering the same immediate tax hit as a withdrawal.
But it was not free money.
A 401(k) loan still needs repayment, usually through payroll deductions. Fidelity notes that, in most cases, 401(k) loans must be repaid within five years, though plan rules control the details [4].
2. 401(k) withdrawal for home purchase
This means taking money out of the account rather than borrowing it.
This was the option that looked simple at first and worse the longer I studied it.
A withdrawal can create income tax consequences. If taken before age 59½, it may also trigger a 10% early distribution tax unless an exception applies. The IRS explains that early distributions are generally subject to a 10% additional tax unless an exception applies [5].
The confusing part is the first-time homebuyer exception.
Many people hear that first-time homebuyers can use retirement money without penalty. That rule is commonly associated with IRAs, not ordinary 401(k) withdrawals. The IRS exception list includes qualified first-time homebuyers up to $10,000, but shoppers need to check which account type and rules apply before assuming a 401(k) home purchase withdrawal is penalty-free [5]. This is one reason the phrase “401k first time home buyer” can be misleading.
3. Drawing from 401k for home purchase through hardship rules
This is a narrower version of the withdrawal question.
Some plans allow hardship distributions for certain immediate and heavy financial needs. But the IRS says plans must specify the criteria used to determine hardship, and a plan may choose to allow some hardship reasons but not others [6].
That means “I want to buy a house” does not automatically mean the plan will approve a hardship withdrawal.
Even when allowed, a hardship withdrawal is not repayable to the plan and may carry tax consequences [2].
4. Not using 401(k) money at all
This was the unexciting option.
It meant delaying the purchase, lowering the home price target, increasing cash savings, asking about down payment assistance, considering FHA/VA/USDA programs where eligible, or buying with a smaller down payment if the mortgage terms still made sense.
This option did not create instant cash.
But it also did not weaken retirement savings.
That tradeoff mattered more after I ran the numbers.
My evaluation criteria
I judged each option using six criteria.
1. Cash access
Could the option actually produce enough money for the down payment or closing-cost gap?
2. Tax cost
Would the strategy create taxable income or a 10% early distribution penalty?
3. Repayment pressure
Would it add another payment on top of a new mortgage?
4. Long-term retirement cost
Would it reduce investment growth and compounding?
5. Job-change risk
Would leaving or losing a job make the situation worse?
6. Homebuying usefulness
Would the money actually improve approval odds or simply make the purchase more fragile?
That last point mattered.
Using a 401(k) to buy a house only makes sense if it makes the whole financial picture stronger.
If it helps with the down payment but leaves no emergency fund, no room for repairs, and a smaller retirement balance, it may solve one problem while creating three more.
What surprised me
The loan felt safer than a withdrawal, but it still had real risk
At first, the 401(k) loan looked clean.
No credit check in the usual consumer-loan sense. No immediate income tax if repaid properly. Interest paid back into the account. Clear repayment schedule.
That seemed reasonable.
But then I looked at the pressure it creates after closing.
A new homeowner already has more expenses:
- mortgage payment,
- property taxes,
- insurance,
- utilities,
- maintenance,
- repairs,
- furnishing,
- moving costs,
- and cash reserves.
A 401(k) loan adds another required repayment stream.
Even if the interest goes back into your own account, the borrowed money is no longer invested the same way during the loan period. Fidelity warns that taking money from a 401(k) can mean missing out on potential market growth, and repayment rules can become a problem if you leave your job [4].
So the loan was not “bad” by default.
But it only looked reasonable if the borrower had stable income, enough cash reserve after closing, and a clear repayment plan.
The withdrawal looked simpler but was usually more expensive
A 401(k) withdrawal felt emotionally easier because there was no loan payment.
But that simplicity was misleading.
A withdrawal can increase taxable income. If the person is under 59½, it may also trigger the 10% additional tax unless an exception applies [5]. Hardship distributions are also not repaid to the account [2].
That means the true cost is not just the amount withdrawn.
The real cost can include:
- federal income tax,
- state income tax where applicable,
- possible 10% additional tax,
- lost retirement growth,
- fewer future compounding years,
- and a permanently lower retirement balance.
That made the withdrawal much harder to justify.
The CARES Act keyword confused the issue
The brief included the keyword “cares act 401k withdrawal for home purchase.”
That makes sense from a search perspective, but it can create confusion.
The CARES Act created temporary coronavirus-related retirement distribution rules in 2020. It was not a standing general homebuyer rule for ordinary 401(k) withdrawals. So someone searching that phrase in the context of buying a house today should be careful not to rely on outdated pandemic-era rules.
Current decisions should be based on today’s IRS rules, the specific plan document, and current tax guidance, not old pandemic relief summaries.
The first-time homebuyer phrase was easy to misunderstand
The phrase “401k first time home buyer” sounds like there should be a clean first-time buyer benefit inside the 401(k).
That was one of the biggest traps.
There is a first-time homebuyer exception commonly discussed for IRAs, up to $10,000, but that does not mean a standard 401(k) withdrawal for a home purchase automatically avoids the 10% early distribution tax. The IRS exception rules need to be checked carefully by account type [5].
This is where I would not trust a short social media answer.
I would check the plan administrator, IRS guidance, and a tax professional.
The mortgage approval question mattered more than I expected
Using 401(k) money does not only affect retirement.
It can also affect the mortgage file.
A lender may want documentation showing where the funds came from, whether they are a loan or withdrawal, and whether the borrower has another payment obligation. A 401(k) loan repayment may affect monthly cash flow, even if it does not behave exactly like a traditional consumer debt in every underwriting situation.
That means the 401(k) decision should happen before the purchase contract, not in panic mode after an offer is accepted.
What actually worked best
The best approach was not a universal yes or no.
It was a decision framework.
Best option if the 401(k) is the only way to close
If the purchase cannot happen without 401(k) money, I would first ask whether the home purchase is too stretched.
That sounds harsh, but it is practical.
A house is not only a down payment problem. It is a long-term cash-flow commitment.
Before using the 401(k), I would ask:
- Will I still have an emergency fund after closing?
- Can I afford the mortgage and 401(k) loan repayment?
- What happens if a repair hits in the first year?
- What happens if I lose or change jobs?
- Am I reducing retirement security for a house that is already at the edge of affordability?
If those answers are weak, the better move may be to pause.
Best option if choosing between loan and withdrawal
If someone has already decided to use 401(k) money, a 401(k) loan often deserves consideration before a withdrawal, if the plan allows loans and the borrower can handle repayment.
The reason is simple: a loan can avoid the immediate tax and penalty problem if it is repaid under the plan’s rules. Fidelity also notes that with a 401(k) loan, the borrower is generally paying the money back into the account, including interest, though the loan still has risks and rules [4].
But I would only consider the loan if:
- the job is stable,
- the repayment fits the budget,
- the loan amount is modest,
- retirement contributions can continue,
- cash reserves remain after closing,
- and the home purchase is still affordable without optimistic assumptions.
Best option if considering a withdrawal
I would treat a withdrawal as a last resort.
A 401(k) withdrawal for home purchase may create taxes, possible penalties, and permanent loss of retirement assets. Hardship withdrawals cannot be repaid to the plan [2].
That does not mean nobody should ever do it.
But I would not do it just to buy sooner.
It might only make sense in a narrow situation where the home purchase is financially stable, the tax impact is understood, the withdrawal is small relative to retirement savings, and there are no better alternatives.
Even then, I would run it past a tax professional.
Best option if there are alternatives
This was the option I liked more by the end.
Before touching the 401(k), I would compare:
- delaying the purchase by 6 to 18 months,
- lowering the price range,
- negotiating seller credits,
- using a down payment assistance program,
- considering FHA financing,
- considering VA or USDA loans if eligible,
- saving tax refunds or bonuses,
- reducing debt-to-income ratio,
- or buying with a smaller down payment if the full payment remains safe.
None of these is perfect.
But they preserve retirement money.
And that matters.
How to draw from 401(k) for home purchase if you still want to explore it
This is the checklist I would use before making any move.
Step 1: Read your plan rules
Not every 401(k) allows loans.
Not every plan allows hardship withdrawals for a home purchase.
The IRS says plans are not required to offer loans, and plans can limit loan availability [7]. Hardship distribution rules also depend on the plan’s criteria [6].
Start with the plan administrator.
Ask:
- Does the plan allow loans?
- Does the plan allow hardship withdrawals?
- Is a primary residence purchase an eligible hardship reason?
- What documentation is required?
- What fees apply?
- What happens if I leave my job?
- Can I keep contributing while repaying the loan?
Step 2: Get the exact loan or withdrawal numbers
Do not estimate from the account dashboard.
Ask for exact numbers:
- vested balance,
- maximum loan amount,
- repayment period,
- interest rate,
- payroll deduction amount,
- fees,
- tax withholding,
- potential penalty,
- and required documentation.
A $20,000 loan and a $20,000 withdrawal are not the same decision.
Step 3: Ask the lender how it affects the mortgage file
Before moving money, ask the mortgage lender how they will treat it.
Ask:
- Will a 401(k) loan payment affect my debt-to-income ratio?
- What documentation do you need?
- Will the funds count as acceptable source of down payment?
- Do I need proof of withdrawal or loan terms?
- Will this change my approval amount?
This prevents last-minute surprises.
Step 4: Calculate the after-tax withdrawal amount
If considering a withdrawal, calculate what you actually keep after taxes and penalties.
A $20,000 withdrawal may not give you $20,000 of usable homebuying cash after withholding and tax impact.
This is where a tax professional can prevent a costly mistake.
Step 5: Calculate the retirement cost
This is the step most people avoid because it is uncomfortable.
Ask:
- What would this money likely become if left invested?
- How many years until retirement?
- Will I reduce future contributions?
- Will I miss employer matching contributions?
- Can I rebuild the balance quickly?
The lost future growth may matter more than the immediate cash.
A practical decision rule I would use
After comparing the options, I would use this rule:
If the 401(k) money is needed because the house barely works, do not use it. If the house already works and the 401(k) loan only bridges a small, temporary gap, it may be worth evaluating carefully.
That is the distinction.
Using a 401(k) to make an unaffordable purchase look affordable is risky.
Using a modest 401(k) loan to solve a temporary liquidity gap may be different, but only if repayment is realistic and retirement progress remains intact.
So, can I use 401k to buy a house?
Yes, you may be able to use a 401(k) to buy a house through a loan or, in some cases, a withdrawal.
But the better answer is:
You can use a 401(k) to buy a house only if your plan allows the method you want, and you should understand the tax, penalty, repayment, and retirement-growth consequences before doing it.
A 401(k) loan is usually less damaging than a withdrawal if repaid properly, but it still creates repayment pressure and investment opportunity cost.
A withdrawal may be simpler, but it can be taxable, may trigger a 10% additional tax if you are under 59½ and no exception applies, and cannot usually be put back into the plan.
Is using 401k to buy a house ever worth it?
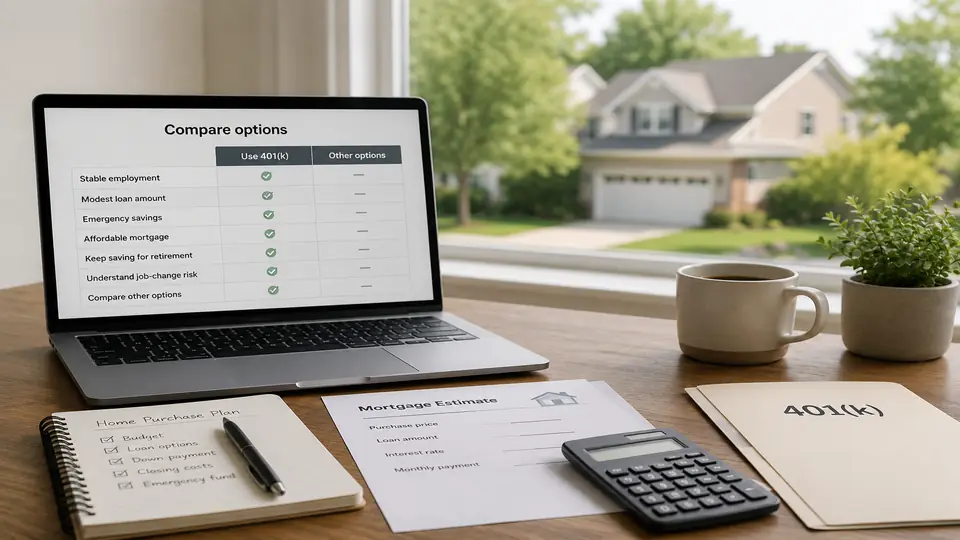
It can be worth evaluating in limited cases.
For example:
- You have stable employment.
- The loan amount is modest.
- You still have emergency savings after closing.
- The mortgage remains affordable.
- You can keep contributing to retirement.
- You understand the job-change risk.
- You have compared other homebuying options.
It is much harder to justify if:
- the purchase is already stretched,
- you would drain retirement savings,
- you would stop retirement contributions,
- you have no emergency fund,
- you expect income instability,
- or you are using the 401(k) to avoid delaying the purchase by a few months.
Final takeaways
I started this test hoping to find a clean answer.
I did not.
What I found was a hierarchy.
First, try not to touch the 401(k).
Second, if you must consider it, compare a loan before a withdrawal.
Third, if you consider a withdrawal, understand taxes, penalties, and the fact that the money may be gone from retirement permanently.
Fourth, do not rely on vague first-time homebuyer advice without checking whether it applies to a 401(k), an IRA, or both.
Fifth, ask the lender and plan administrator before moving money.
The real issue is not whether a 401(k) can help buy a house.
It can.
The real issue is whether the house still makes sense after the retirement cost, tax cost, repayment risk, and lost flexibility are included.
That is the test I would use before touching retirement money.
If the numbers only work after weakening retirement security, I would wait.
If the numbers still work after a cautious 401(k) loan analysis, then I would treat it as a serious financial decision, not a shortcut.